Don't miss a gem
The claim targets a non-operating subsidiary but arrives as Petra considers asset sales and new financing
Two announcements in less than 24 hours have brought Petra Diamonds’ financial position into sharper focus
On 1 October, the company launched a strategic review to address its immediate liquidity requirements. The possible outcomes include a sale process involving company assets.
The following day, Petra disclosed that HM Revenue & Customs had advertised a winding-up petition against Petra Diamonds UK Treasury Limited over £5,647,811.32 in unpaid corporation tax.
The petition does not directly concern Petra’s mines. It nevertheless arrives at a sensitive point for a group already negotiating with creditors, seeking refinancing and considering how much of its business it can continue to support.
Petra Diamonds UK Treasury is a wholly owned, indirect subsidiary of the group. According to Petra, it is a non-operating company and does not own or operate any of its mining assets.
The corporation-tax liability relates to the financial year ended 30 June 2025. It arose from interest income accrued on a receivable due from Ealing Management Services, another wholly owned Petra subsidiary.
The unusual detail is that Petra Diamonds UK Treasury recorded the interest as income even though it had not received the money from its affiliate. The tax liability was therefore created by accrued income rather than cash that had entered the subsidiary.
HMRC has now taken the matter to the High Court. The petition is scheduled to be heard on 14 October 2026.
This remains a winding-up petition, not a winding-up order. The court has not placed the subsidiary into compulsory liquidation, and Petra has said it is assessing the implications for the group’s financing arrangements and continuing refinancing discussions.
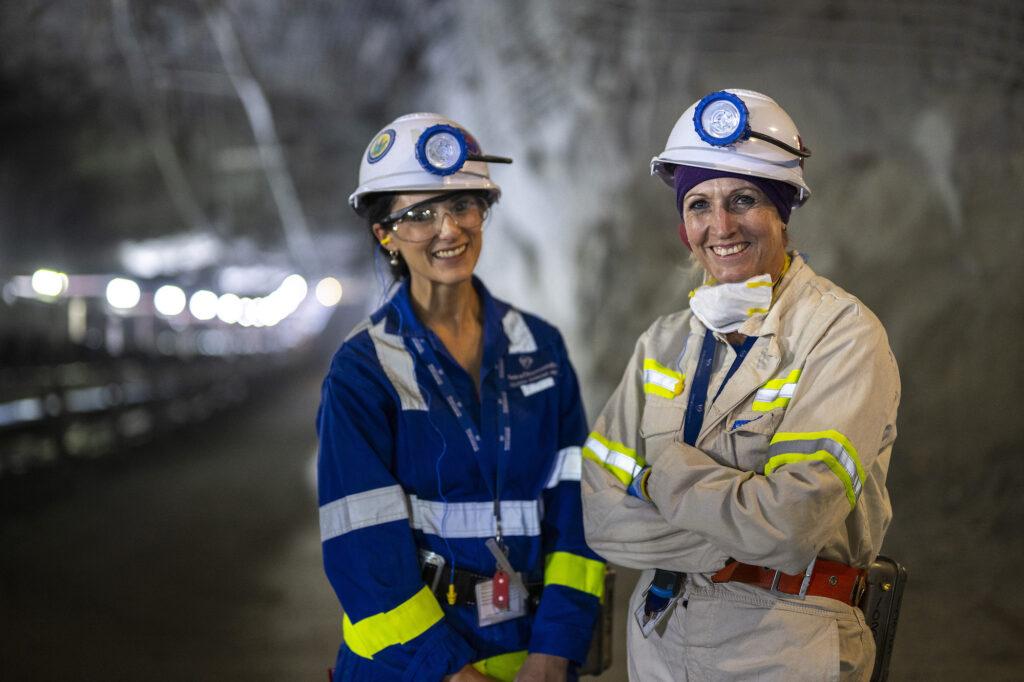
Petra Diamonds employees working underground at one of the group’s South African mining operations. | Image: Petra Diamonds
Petra has drawn a clear distinction between the treasury subsidiary and its operational businesses.
Neither Petra Diamonds UK Treasury nor Ealing Management Services owns or operates the group’s mines. The petition does not directly place Cullinan or Finsch into insolvency proceedings, nor does it mean that Petra Diamonds Limited itself is being wound up.
That distinction is essential, but it does not make the petition irrelevant to the wider group.
A treasury subsidiary exists within the financial structure through which money, debt and obligations move around a corporate group. Formal action by a creditor against such an entity can therefore matter to lenders and other stakeholders even when the company concerned has no mining equipment, employees or producing assets of its own.
Petra has acknowledged this by stating that it is examining what the petition could mean for its financing arrangements.
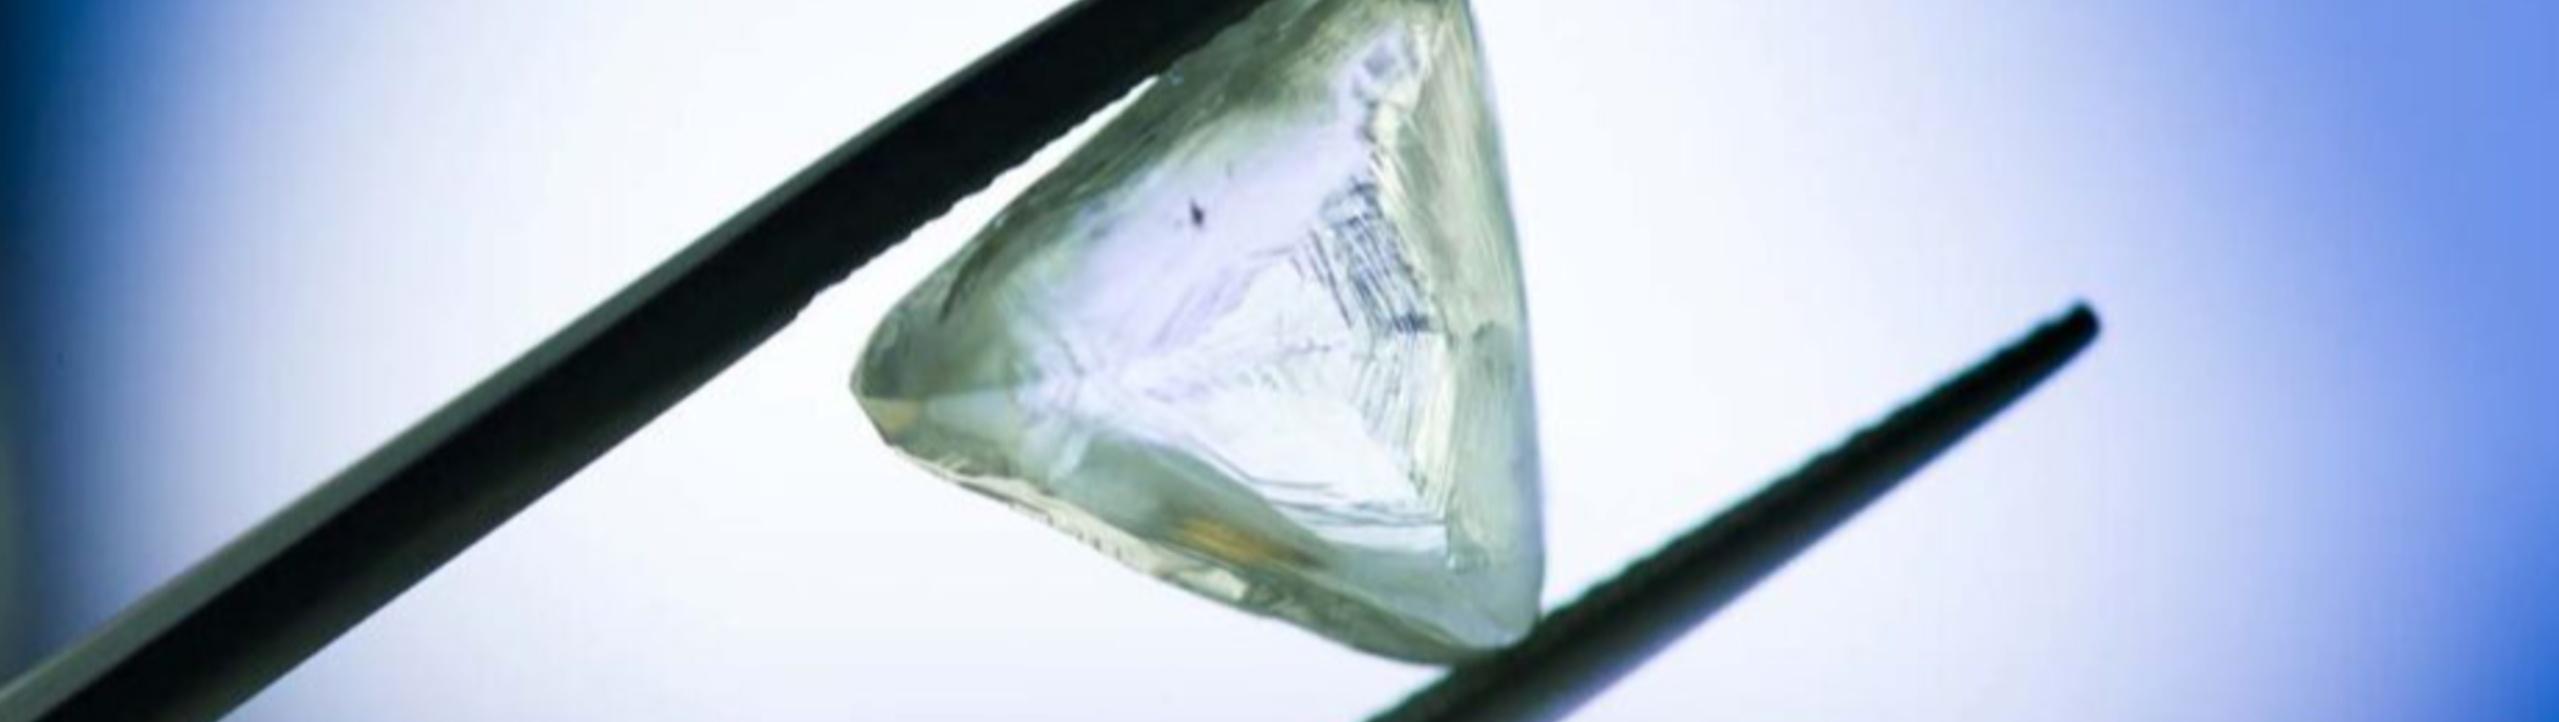
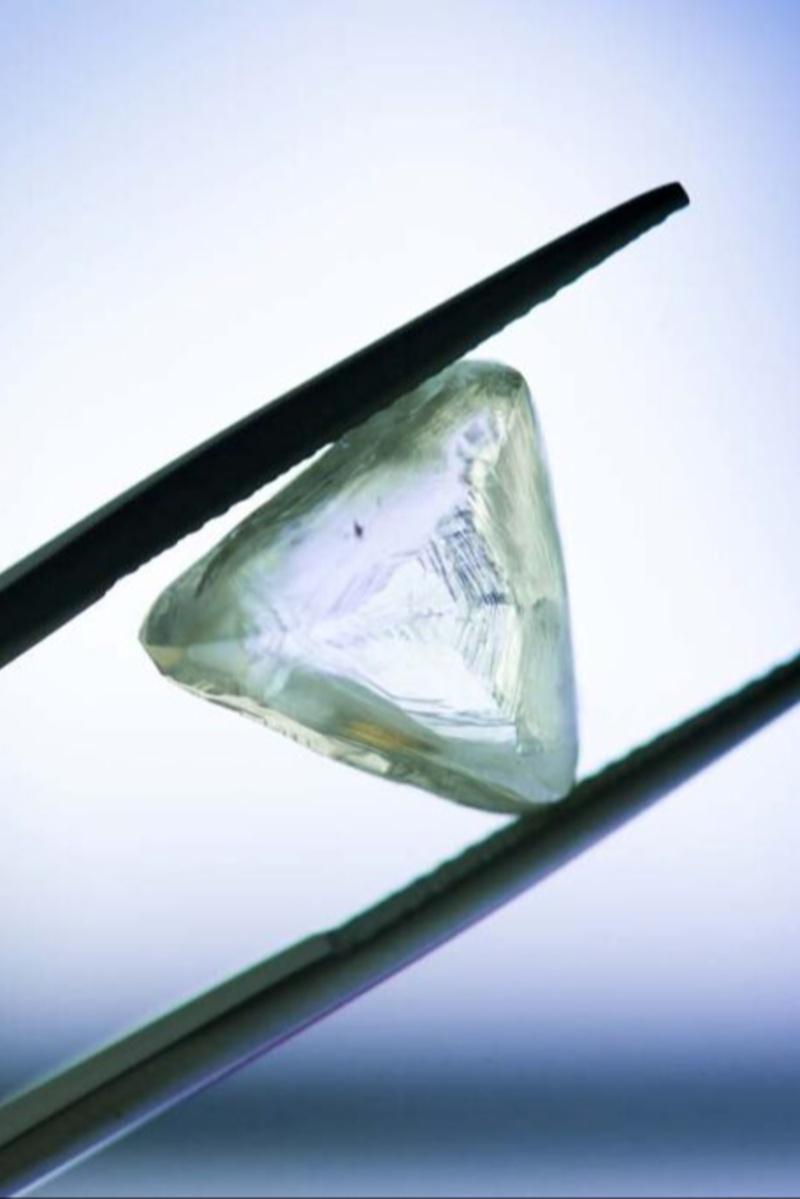
Petra Diamonds supplies gem-quality rough diamonds to the international jewellery market. | Image: Petra Diamonds
The petition followed Petra’s announcement of a strategic review by one day.
The review was launched after consultation with key stakeholders, including the company’s first- and second-lien creditors. Petra said it would consider all available routes for meeting the business’s near-term liquidity needs, including a potential sale process involving its assets.
No decision to sell Cullinan has been announced, and Petra has cautioned that there is no certainty about the outcome of the review. However, Cullinan is now described by the company as its principal operating asset, giving any reference to potential asset sales considerable significance.
The review was accompanied by a change at the top of the board. José Manuel Vargas stepped down as chair and director on 1 October, with Lerato Molebatsi assuming the role of interim chair.
Petra is finalising the appointment of a financial adviser to assist with the process.
Workers review plans at a construction project connected to Petra Diamonds’ community-partnership programme. | Image: Petra Diamonds
The tax petition is relatively modest when compared with Petra’s wider debt, but it forms part of a much larger liquidity problem.
At 30 June 2026, Petra reported consolidated net debt of $322 million, up from $298 million three months earlier. Its ZAR1.75 billion revolving credit facility, reported at approximately $107 million, was fully drawn.
The company said cash remained tight following weaker prices achieved during its fourth-quarter diamond tenders and the ring-fencing of cash associated with the Finsch business-rescue process.
Revenue for the 2026 financial year was $206 million from the sale of approximately 2.29 million carats. Although annual revenue was unchanged, fourth-quarter revenue fell to $38 million from $68 million in the preceding quarter.
The group’s average price during the final quarter was $69 per carat. At Cullinan, the quarterly average fell to $77 per carat, although the mine’s annual average improved to $106 per carat because of its higher-value product mix and the contribution of exceptional stones.
Petra has increasingly focused Cullinan’s production on areas expected to yield a greater proportion of large and fancy-coloured diamonds. These stones have shown more resilience than the smaller categories facing structural price pressure, but they cannot entirely insulate the group from the wider market.
A gem-quality rough diamond from Petra Diamonds’ production portfolio. | Image: Petra Diamonds
Petra secured additional assistance from its senior lender in July.
Approximately $6 million of cash interest due that month was deferred until January 2027. The lender also provided an additional ZAR300 million working-capital facility, equivalent at the time to approximately $18 million.
That support came with a requirement for Petra to begin refinancing discussions during the second half of September, with the aim of agreeing non-binding commercial terms by the end of October.
If those discussions do not produce an agreement, the senior lender has the option to initiate an asset-sale process. It can also request the appointment of a chief restructuring officer and the creation of an independent restructuring committee reporting to the board.
The strategic review announced on 1 October suggests that the company has reached the stage at which those possibilities must be considered directly.
Petra completed an extensive refinancing in 2025.
That transaction extended the maturity of its senior secured bank debt to December 2029 and its loan notes to March 2030. It also included a rights issue intended to raise approximately $25 million.
The refinancing gave Petra more time, but additional time cannot by itself resolve the pressure created when operating cash generation falls below the demands of debt, capital expenditure and mine development.
During June 2026, a $13 million coupon on Petra’s loan notes was settled through the issue of new shares rather than cash. The use of equity preserved liquidity but also illustrated how carefully the group was already managing its available cash.
The subsequent working-capital facility, interest deferral, strategic review and HMRC petition now form a sequence rather than a collection of isolated events.
The group’s difficulties are also visible at mine level.
Finsch entered business rescue in May 2026, with production subsequently suspended. Petra said the mine’s high proportion of smaller diamonds, combined with weak prices and a strong South African rand, had made the operation financially untenable despite its underlying operational performance.
The experience at Finsch demonstrates how quickly an operating mine can become unsustainable when its product mix is exposed to the weakest part of the market.
That leaves Cullinan at the centre of Petra’s future. Its exceptional diamonds and greater exposure to high-value production give it strategic strength, but maintaining an underground mine still requires continuing capital investment.
Any restructuring must therefore balance short-term liquidity against the need to preserve the asset capable of generating Petra’s greatest long-term value.
The HMRC petition is not evidence that Petra’s mines are being wound up, and it should not be reported as such. It concerns one non-operating subsidiary and must still be considered by the court.
Its importance lies in its timing.
A £5.65 million tax claim has entered formal court proceedings just as Petra is seeking a refinancing solution, engaging with secured creditors and examining whether assets may need to be sold. It adds another obligation to a group already working within narrow financial margins.
For the wider diamond industry, this is another indication that the current downturn is no longer measured only in lower prices and reduced margins. It is affecting corporate structures, employment, mine ownership and the ability of producers to fund operations through a prolonged period of weakness.
Petra’s position is not determined by the petition alone. The more consequential question is whether the company can reach an agreement with its financial stakeholders while preserving the value of Cullinan.
The court hearing on 14 October is the next immediate event. The strategic review will decide the larger story.
Read Petra Diamonds’ announcement concerning the HMRC petition.
INSIGHTSJUL 19, 2025
UK Jewellery Sector Demands Government Action for Small Businesses
UK jewellery and allied craft leaders unite to call for urgent government reform, highlighting the structural challenges facing small and microbusinesses.
READ MORE
GJEPCJUL 27, 2025
A Pact Signed in Power — and Sealed in Gold
India–UK FTA signed by Modi and Starmer unlocks $2.5bn trade vision for Indian jewellery exports
READ MORE
INDUSTRY & POLICYAUG 8, 2025
Tariff Shock – What Trump’s 50% Duties Mean for India’s Gold, Jewellery & Diamond Trade
India’s jewellery and diamond industries face unprecedented pressure as US tariffs jump to 50%, prompting official backlash and rapid readjustments in trade strategies.
READ MORE